






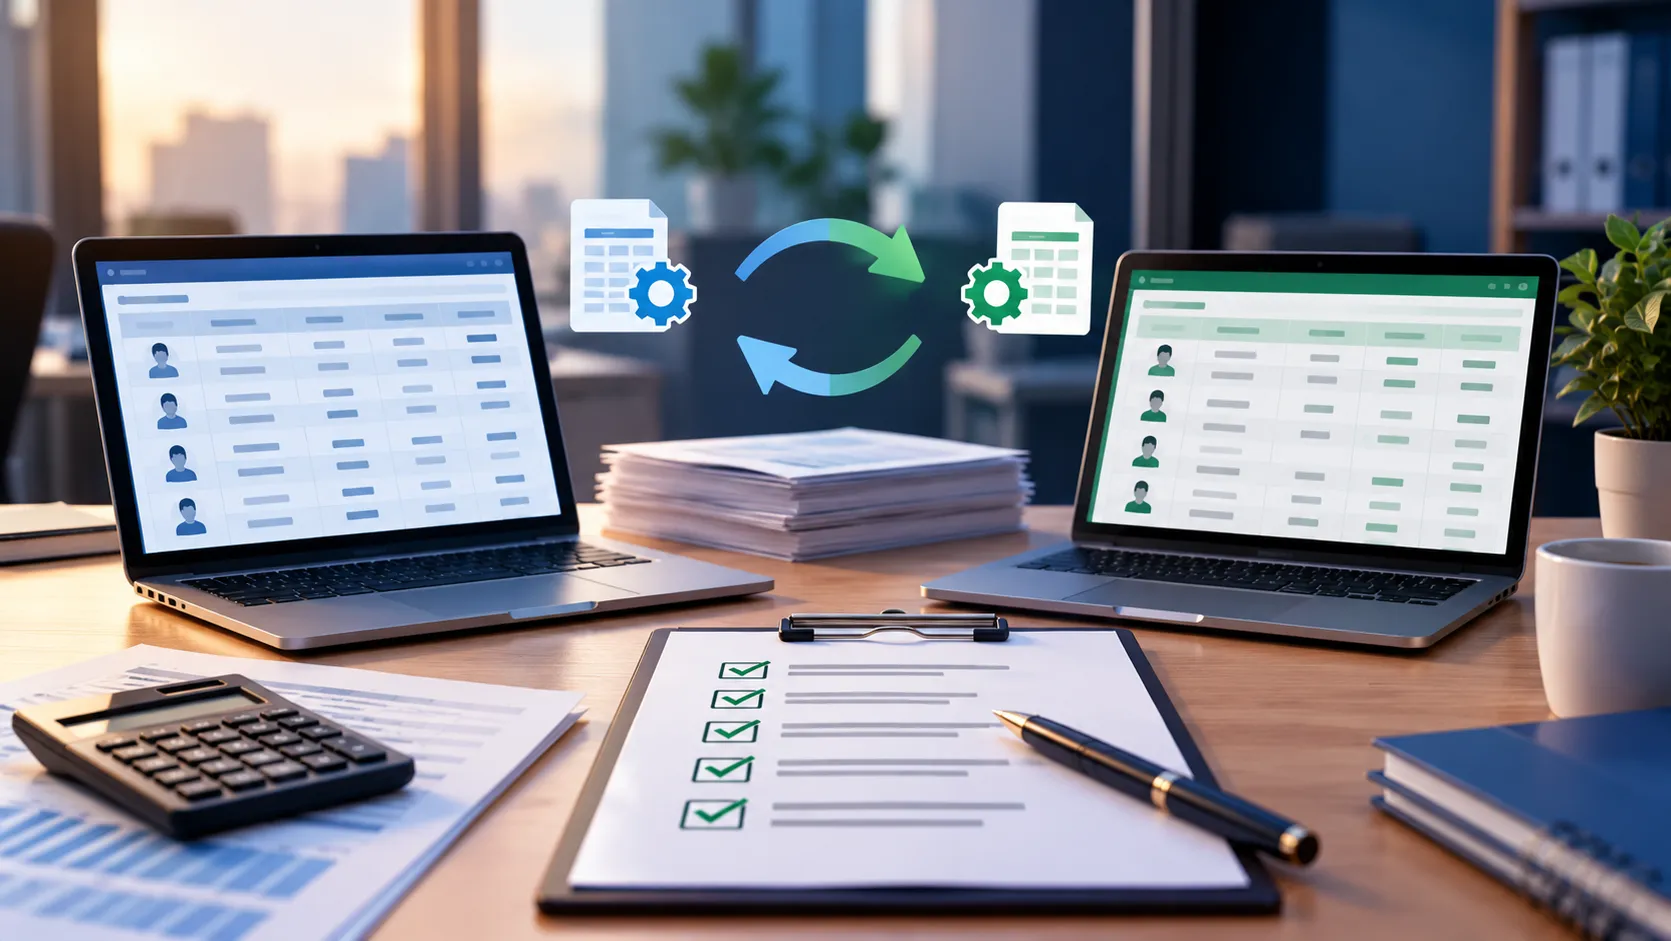
A mid-size business ran a parallel payroll cycle before switching providers, and the company-level totals balanced to the dollar. Underneath that match, one employee had been paid $120 short and another $120 over, and both errors were still live when the new system went live.
That is what a payroll reconciliation built on company totals alone will miss. Six specific checks catch what totals hide.
What Is a Parallel Payroll Run?
A parallel payroll run means processing the same pay period through both the old and new payroll systems at the same time, before the new system takes over live payments.
The point is not to confirm that company-level net pay matches. Net pay can match while taxes, deductions, and employer costs are each wrong in offsetting directions, which is why reconciliation has to happen at the employee level, not just the total.
A parallel run also needs to identify which system is authorized to make the real payment while the other stays nonpaying. Submitting two live payrolls just to compare bank outputs creates a duplicate payment risk the exercise was meant to prevent.
Check 1: Employee-Level Gross-to-Net Comparison
Compare gross pay, taxable wage bases, withholding, deductions, and net pay for each employee separately, not just the company total.
Reproducing an old system’s mistake in the new system is not a successful match either. If the legacy system miscalculated overtime for a role, carrying that error into the new system passes a company-total comparison while leaving the underlying error in place.
- Pull employee-level output from both systems for the same pay period.
- Flag every line where gross, tax, or net differs, even by a small amount.
- Investigate differences individually instead of netting them against each other.
This is the same discipline behind payroll reconciliation risk in an ongoing pay cycle, applied once, under pressure, before a cutover date.
Check 2: Tax Withholding and Deposit Handoff
Tax withholding accuracy and the tax deposit and filing handoff are two separate checks, and treating them as one is where liability gets missed.
An employer generally remains responsible for federal employment tax obligations even when a provider is filing on their behalf. A payroll taxes mapping error in a shared rule can pass unnoticed in early testing and then affect every employee under that rule once it is live.
Check 3: Deduction and Benefit Mapping
Garnishments and benefit deductions need a tighter tolerance than gross payroll totals, because an error here is a legal exposure, not a rounding issue.
A missing garnishment and an incorrect withholding amount can offset each other in net pay while both obligations remain wrong. Reviewing each deduction by its effective date, order, and tax treatment, through the same payroll services process used for the live run, catches what a net-pay match alone cannot.
A benefit deduction mapped to the wrong category can also change totals for employees who were never touched by the original error, which is why category-level checks matter as much as dollar-level ones.
Check 4: Year-to-Date Balance Migration
Year-to-date balances must be verified independently of current-period earnings, not assumed correct because a migration file was imported without errors.
A successful import confirms the file was ingested, not that the balances inside it are accurate. The most common failure is disagreement on the cutoff date, where one file includes the final legacy payroll run and another stops one cycle earlier, a gap worth checking against the same logic used in a payroll system setup from scratch.
Check 5: Retro Pay and Off-Cycle Activity
Retro adjustments, corrections, and off-cycle payments behave differently from system to system, and they are the area most often skipped in a parallel run.
Include at least one parallel cycle that carries real retro activity, not just a clean standard pay period. A business running employer of record services for part of its workforce should confirm retro handling works the same way across both populations before cutover, not after.
Check 6: Formal Sign-Off and Rollback Plan
Go-live needs documented sign-off from each function involved, not a single approval from whoever is managing the project.
- HR confirms the configuration matches the current policy.
- Payroll confirms calculations, controls, and processes.
- Finance confirms funding readiness and general ledger alignment.
- IT confirms integrations and job schedules are stable.
Set variance tolerances before testing starts; the tightest for taxes and garnishments, looser only where policy allows it for totals. A US payroll rollback plan should define in advance what triggers a delay, not leave that decision for the day of cutover.
How Procloz Supports Payroll Transitions in the US
Procloz manages payroll transitions with employee-level reconciliation built into every parallel cycle, not just a company-total comparison at the end.
Tax withholding, deductions, and year-to-date balances are each verified independently before a cutover date is confirmed. That structure is what Procloz applies across every provider switch and system migration it supports, not as a one-time check but as the standard transition process.
A Clean Parallel Run Is Checked, Not Just Balanced
A parallel payroll run that balances at the company level has not yet proven anything about individual accuracy.
The six checks above work because they look underneath the total, at the employee level, where the real errors live.
Contact us for assistance now.
Payroll Reconciliation in the USA Frequently Asked Questions
Q: What is payroll reconciliation during a parallel run?
A: It is the process of comparing gross pay, taxes, deductions, and net pay between an old and new payroll system at the employee level, not just at the company total.
Q: Why isn’t a matching company-level net pay enough?
A: Because individual payroll errors can offset each other. One employee overpaid and another underpaid can net to zero at the company level while both employee records remain genuinely wrong underneath.
Q: Who stays liable for payroll tax errors during a transition?
A: The employer generally does, even when a provider handles tax filing on their behalf. Procloz verifies tax withholding and deposit handoffs separately as part of every payroll transition it manages.
Q: How many parallel cycles should a business run before go-live?
A: Enough to include at least one full cycle with real retro pay or off-cycle activity, since clean standard periods alone will not surface how each system actually handles pay corrections.
Q: What should a payroll rollback plan include?
A: Defined triggers for delaying go-live and agreed in advance with HR, Payroll, Finance, and IT leadership together. Procloz builds this exact function-level sign-off structure into every payroll transition it directly manages.