






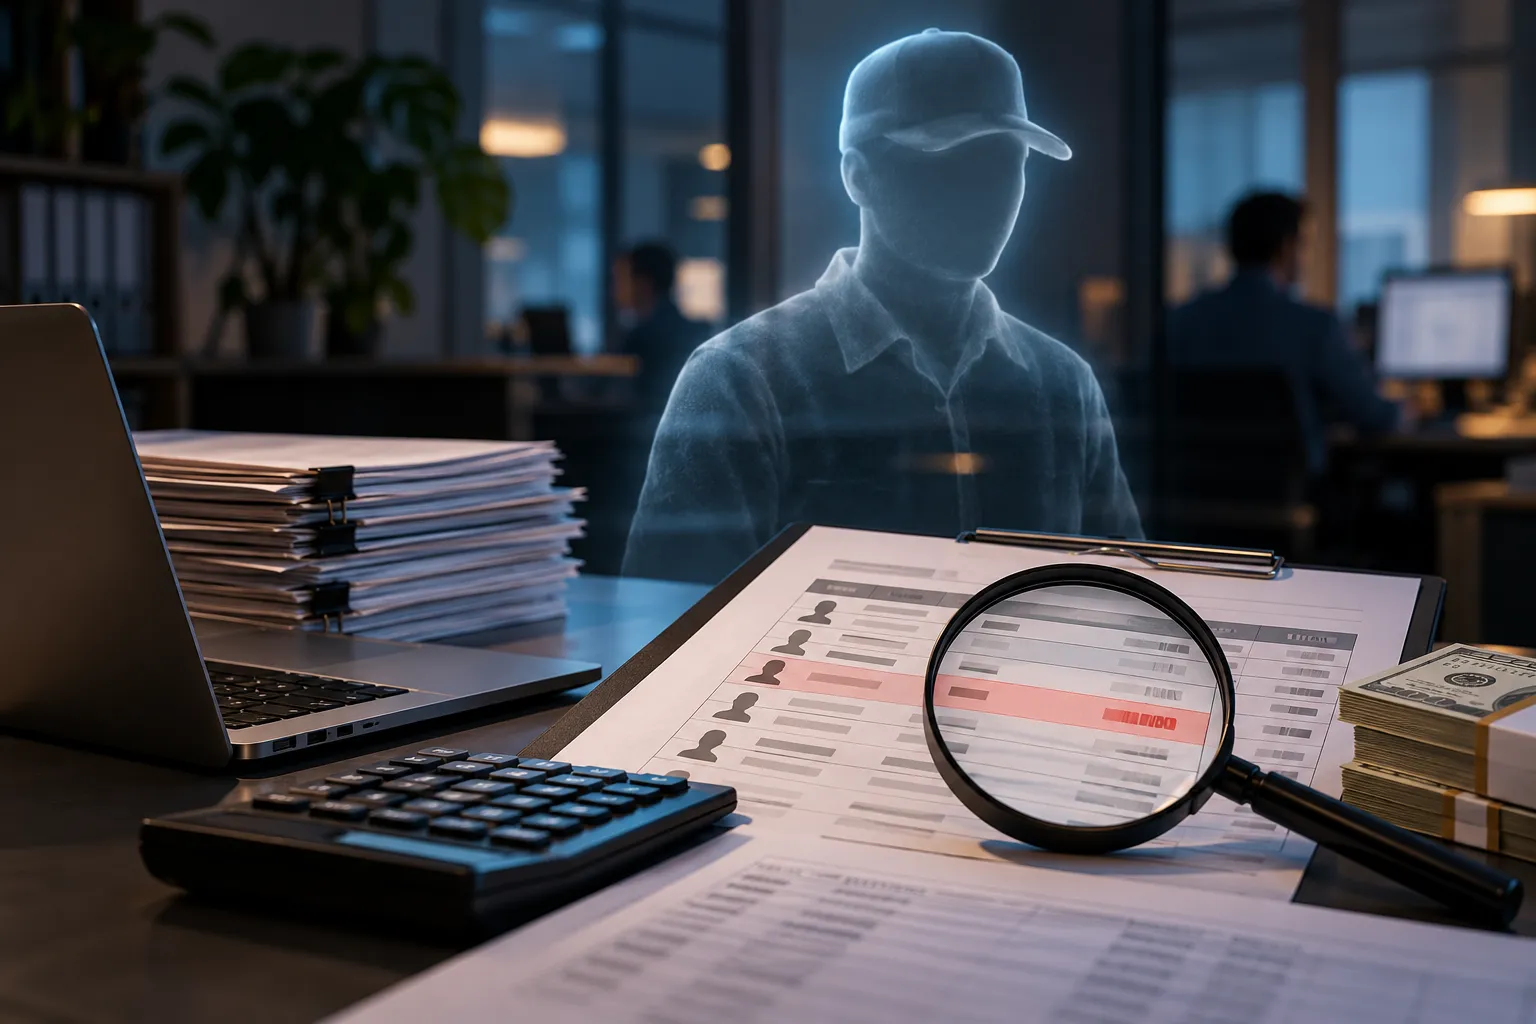
A payroll audit at a mid-size logistics company found a warehouse worker who had not clocked in for fourteen months. The pay checks never stopped, and nobody had checked why.
That gap is how ghost employee fraud survives inside an otherwise normal payroll run. Seven specific signals usually give it away if someone is looking for them.
What Is a Ghost Employee on a US Payroll?
A ghost employee is a fictitious or no-longer-active worker kept on payroll so their wages can be diverted to someone else’s account.
The wages are not a victimless paper entry. Every dollar paid to a ghost employee still generates real Federal Insurance Contributions Act (FICA) tax, Federal Unemployment Tax Act (FUTA) liability, and state unemployment insurance contributions the employer has to account for and later unwind.
According to the Association of Certified Fraud Examiners (ACFE), payroll fraud carries a median loss of $50,000 per case and typically takes around 18 months to detect. By the time it surfaces, the payroll fraud risks have usually compounded across several reporting periods.
Signal 1: Duplicate Direct Deposit Details
More than one employee record pointing to the same bank account is one of the clearest signals of a ghost employee.
A legitimate payroll will almost never show two active staff with identical direct deposit numbers. When it does, the explanation is rarely innocent.
- Run a payroll report sorted by bank account number, not employee name.
- Flag any account that appears against more than one employee ID.
- Treat a shared payroll services account as a stop-and-verify event, not a formatting error.
Signal 2: Matching Addresses, Phone Numbers, or Social Security Numbers
A ghost employee record is usually built from a real person’s details, reused with small variations.
Two employees sharing a mailing address, a phone number, or a Social Security number is rarely a coincidence worth ignoring. This pattern is especially common when the same person who creates payroll records also approves them.
Signal 3: Missing W-4 or I-9 Paperwork
Every legitimate US employee has a completed Form W-4 for tax withholding and a Form I-9 confirming work eligibility on file before their first pay check.
A payroll entry without either document attached has likely never been through a real onboarding process. Cross-checking payroll headcount against signed payroll taxes documentation on file is one of the fastest ways to surface a gap.
Signal 4: No Benefits Enrolment or PTO Ever Used
A real employee eventually enrols in benefits, requests time off, or files a reimbursement.
A payroll record that has run for a year without a single benefits election or a single day of paid time off (PTO) taken stands out once it is checked against those US payroll activity logs. It is not proof of fraud by itself, but it is a reason to look closer.
Signal 5: No Supervisor Contact or Performance Record
A ghost employee has no real manager relationship because there is no real person attending meetings or receiving feedback.
Look for an employee with no performance review on file, no emails tied to their work account, and a supervisor who cannot describe a recent interaction with them.
Any one of these alone can be an oversight. All three together point somewhere specific.
Signal 6: A Headcount Mismatch Against the Org Chart
Payroll headcount and the actual organizational chart should match, and a gap between the two is a structural warning sign, not a rounding error.
Comparing payroll output against department headcount sheets is a standard step in any payroll security audit, and discrepancies tend to cluster in businesses with high staff turnover or distributed worksites, where a departure is easy to miss and a new name is easy to add unnoticed.
Signal 7: One Person Controls the Full Payroll Cycle
The structural root of most ghost employee cases is the same person adding a record, approving it, and releasing payment, with no second set of eyes anywhere in between.
According to ACFE data, payroll fraud rates run higher in sectors like transportation, warehousing, retail, and technology, where decentralized teams and fast hiring cycles make that single point of control more common. Separating who can create a payroll record from who can approve payment is the single most effective structural fix, which is also the gap that employer of record services are built to close by design.
How Procloz Supports Payroll Compliance in the US
Procloz manages payroll operations with built-in separation between record creation, approval, and payment release, so no single person controls the full cycle.
Every pay run is reconciled against signed onboarding documentation and active headcount records before payment is released. That structure is what Procloz applies across every state and industry a business operates in, not as a one-time audit step but as the ongoing payroll process itself.
Seven Signals, One Missing Control
Every signal in this list points back to the same structural gap: one person with unchecked control over who gets added to payroll and who gets paid.
Catching ghost employee fraud early starts with checking payroll data against real activity, not waiting for an annual audit to surface it.
Contact us for assistance now.
Ghost Employee Fraud in the USA Frequently Asked Questions
Q: What is ghost employee fraud?
A: Ghost employee fraud is when a fictitious or inactive worker is kept on payroll so their wages are diverted elsewhere. It typically surfaces through duplicate deposit details, missing paperwork, or a headcount mismatch.
Q: How much does ghost employee fraud typically cost a business?
A: ACFE data puts the median loss from payroll fraud at $50,000 per case, with detection typically taking around 18 months. Procloz structures payroll with checks designed to catch this earlier.
Q: Does a ghost employee create real tax liability?
A: Yes. Wages paid to a ghost employee still generate real FICA, FUTA, and state unemployment tax obligations the employer must later account for and unwind once the fraud is discovered.
Q: What is the single best control against ghost employee fraud?
A: Separating who can add a payroll record from who approves and releases payment. Procloz builds this separation into its payroll operations so no single individual controls the entire cycle alone.
Q: Which industries face higher ghost employee fraud risk?
A: ACFE data shows elevated payroll fraud rates in transportation, warehousing, retail, and technology, sectors where decentralized teams and fast, high-volume hiring cycles are especially common across the United States today.